
In past work, we confirmed that buying and selling in U.S. Treasury securities is changing into more and more focused on the final buying and selling day of every month. On this publish, we present that buying and selling can also be changing into extra concentrated round the designated pricing, or “strike,” occasions for fixed-income indexes. The focus is particularly pronounced on month-end buying and selling days. We additionally doc a marked shift in buying and selling exercise from round 3 p.m. (ET) to round 4 p.m. after a significant fixed-income index supplier moved its strike time from 3 p.m. to 4 p.m. in January 2021.
Finish-of-Month Trading, Index Rebalancing, and Index Strike Instances
In an earlier LSE post, we discovered that general Treasury safety buying and selling quantity is about 58 p.c larger on the final buying and selling day of the month than on different days. We confirmed in a related post that this focus of exercise has elevated sharply over the previous decade or so and is related to improved market liquidity. We conjecture that the elevated focus of exercise might mirror the progress of belongings managed relative to fixed-income indexes, lots of that are rebalanced at month-end.
In contrast to the fairness market, the Treasury market is over-the-counter and has no exchange-mandated closing time. As a substitute, index suppliers have discretion as to what time of day to set their closing costs. Traditionally, 3 p.m. was the business commonplace (amongst different causes, open-outcry buying and selling for Treasury futures ended at 3 p.m. and the 3 p.m. strike time allowed for a lead time earlier than mutual funds’ internet asset worth manufacturing time of 4 p.m.). On January 14, 2021, Bloomberg Barclays—one in all the largest suppliers of fixed-income indexes (and now referred to as Bloomberg Mounted Earnings Indices)—modified the strike time for its U.S. dollar-denominated indexes from 3 p.m. to 4 p.m. Some reports counsel that one motive for the change was to scale back monitoring error for funds which might be required to cost portfolios utilizing 4 p.m. costs.
Empirical Method
We measure the share of every day’s buying and selling quantity executed in the ten-minute home windows round the 3 p.m. and 4 p.m. index strikes and observe these shares over time. We do that for all days as a gaggle and for end-of-month days when fixed-income indexes are rebalanced. We additionally evaluate intraday buying and selling patterns earlier than and after Bloomberg modified its strike time. Our evaluation covers buying and selling exercise in the most not too long ago auctioned (that’s, on-the-run) notes and bonds in the interdealer market.
Trading More and more Concentrates at the Close
The chart under reveals that the share of each day buying and selling quantity in the ten minutes round 3 p.m. elevated from a mean of two.3 p.c in 2016 to three.4 p.c in 2020. When Bloomberg’s strike time modified from 3 p.m. to 4 p.m. in January 2021, the share of exercise round 3 p.m. plunged, and the share of exercise round 4 p.m. (which had additionally been rising from 2016 to 2020) surged. The share of exercise round 4 p.m. has since elevated from a mean of two.5 p.c in 2021 to three.5 p.c in 2025.
Trading Now Concentrates Round the 4 P.M. Closing Strike
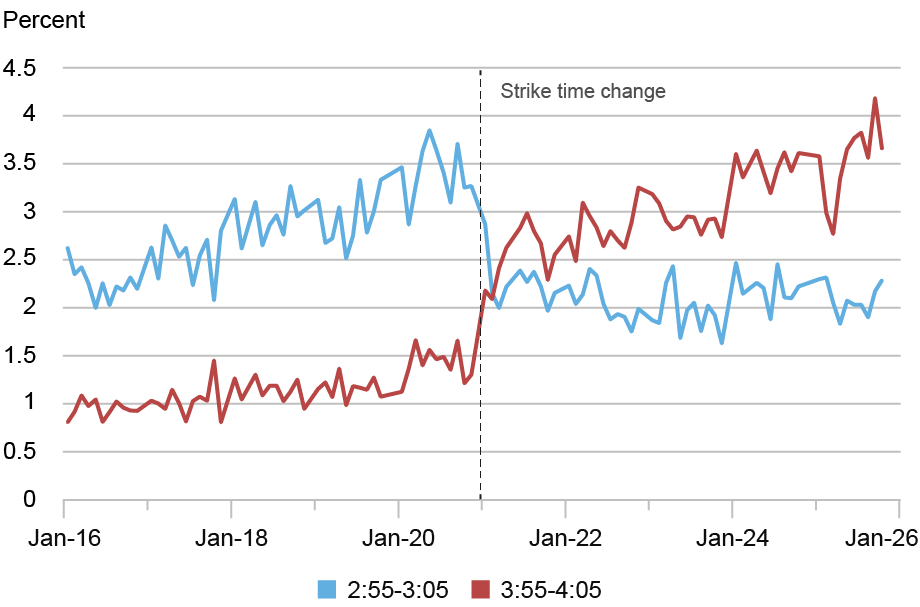
Observe: The chart plots the common share of each day buying and selling quantity in the most not too long ago auctioned Treasury notes and bonds from 2:55-3:05 p.m. and from 3:55-4:05 p.m. for every month from January 2016 to December 2025 (excluding days with an early market shut and months during which the final buying and selling day has an early shut).
Results Extra Pronounced on the Final Day of the Month
As proven in the subsequent chart, buying and selling quantity is much more concentrated round the day-end strike occasions on the final buying and selling day of every month, when indexes are rebalanced. The share of exercise round 3 p.m. on such days elevated from a mean of 8.1 p.c in 2016 to 12.1 p.c in 2020. When Bloomberg’s strike time modified in January 2021, the share of exercise round 3 p.m. plunged, and the share of exercise round 4 p.m. (which had additionally been rising from 2016 to 2020) surged. The share of exercise round 4 p.m. has since elevated from a mean of 11.6 p.c in 2021 to twenty.4 p.c in 2025.
Finish-of-Day Trading Is Extra Pronounced on the Final Day of the Month
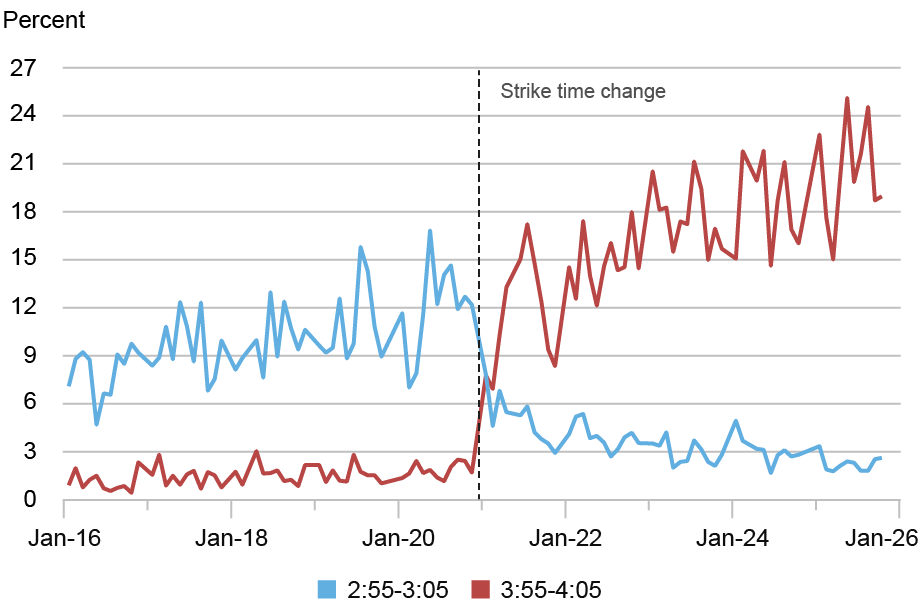
Observe: The chart plots the share of each day buying and selling quantity in the most not too long ago auctioned Treasury notes and bonds from 2:55-3:05 p.m. and from 3:55-4:05 p.m. on the final buying and selling day of every month from January 2016 to December 2025 (excluding days with an early market shut).
Results Are Altering the Intraday Sample of Exercise
The rising share of day-end buying and selling and the elevated significance of the 4 p.m. strike time are mirrored in adjustments in the intraday sample of buying and selling exercise. The subsequent chart plots the common share of each day buying and selling quantity in every five-minute interval from 7 a.m. to five:30 p.m. in 2016 and 2025. In 2016, buying and selling quantity spiked at the 8:30 and 10 a.m. release times of macroeconomic announcements, when auction results were released shortly after 1 p.m., and round the 3 p.m. strike time. There have been a lot smaller spikes round 4 p.m. and 5 p.m.
Trading Exercise Spikes at the Day-Finish Strike Instances
Notes: The chart plots the common share of each day buying and selling quantity in the most not too long ago auctioned Treasury notes and bonds for every five-minute interval from 7 a.m. to five:30 p.m. in 2016 and 2025 (excluding days with an early market shut). Grey bars denote overlap in shares between 2016 (blue) and 2025 (gold). Instances point out interval beginning occasions.
In 2025, the sample is generally related, however the 4 p.m. spike is rather more pronounced. Curiously, the 3 p.m. spike is of comparable magnitude throughout the two years, however quantity shares are then larger in 2025 for each interval from 3:10 p.m. to five:05 p.m., and particularly in the ten minutes round 4 p.m.
Our final chart compares the intraday patterns on month-end days in 2016 and 2025. We discover a lot bigger day-end spikes on as of late, particularly in 2025, per our earlier outcomes. The half-hour interval between 3:45 and 4:15 p.m. thus accounts for multiple quarter of whole each day exercise on month-end days in 2025, on common, with about half of that between 3:55 and 4:00 p.m. alone. These are unusually excessive buying and selling quantity days to start with, as defined earlier.
Finish-of-Day Trading Exercise Spikes A lot Extra on the Final Day of the Month
Notes: The chart plots the common share of each day buying and selling quantity in the most not too long ago auctioned Treasury notes and bonds for every five-minute interval from 7 a.m. to five:30 p.m. on the final buying and selling day of every month in 2016 and 2025 (excluding days with an early market shut). Grey bars denote overlap in shares between 2016 (blue) and 2025 (gold). Instances point out interval beginning occasions.
A common observe about our intraday evaluation is that there’s round-the-clock buying and selling in the market—as mentioned in this article. We select to plot the patterns for 7 a.m. – 5:30 p.m. solely as a result of such hours account for the overwhelming share of each day buying and selling quantity and since U.S. macroeconomic bulletins and different essential occasions (together with U.S. Treasury auctions and end-of-day strike occasions) happen throughout these hours.
Summing Up
We discover that buying and selling exercise in the U.S. Treasury market is more and more concentrated round the end-of-day index strike occasions. That is very true on the final buying and selling day of every month when indexes are rebalanced, complementing our earlier findings of sharply elevated buying and selling on these days extra typically. We additional discover a marked redistribution of buying and selling exercise from round 3 p.m. to round 4 p.m. when a significant fixed-income index supplier moved its strike time from 3 p.m. to 4 p.m. These outcomes present robust proof that index pricing conventions materially form when Treasury buying and selling happens.
Henry Dyer, a former analysis analyst in the Federal Reserve Financial institution of New York’s Analysis and Statistics Group, is pursuing a grasp’s in finance at the MIT Sloan Faculty of Administration.
Michael J. Fleming is head of Capital Markets in the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.

Or Shachar is a monetary analysis advisor in the Federal Reserve Financial institution of New York’s Analysis and Statistics Group.
The best way to cite this publish:
Henry Dyer, Michael J. Fleming, and Or Shachar, “Treasury Trading at the Close,” Federal Reserve Financial institution of New York Liberty Road Economics, September 22, 2026, https://doi.org/10.59576/lse.20260922
BibTeX: View |
Disclaimer
The views expressed on this publish are these of the creator(s) and don’t essentially mirror the place of the Federal Reserve Financial institution of New York or the Federal Reserve System. Any errors or omissions are the accountability of the creator(s).