
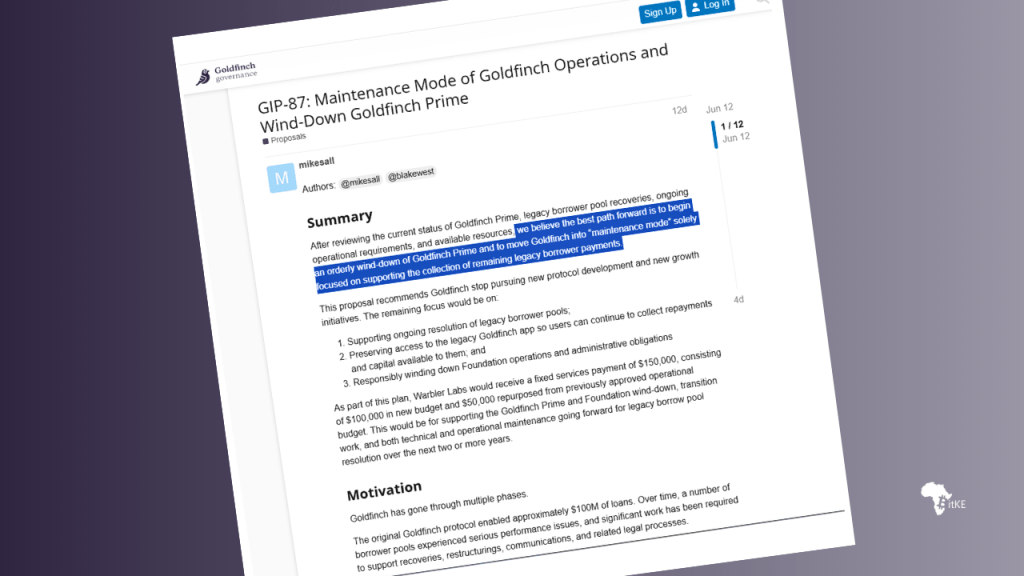
GoldFinch, one of decentralized finance’s most distinguished real-world asset (RWA) lending protocols, is winding down operations after years of trying to convey non-public credit score on-chain.

The protocol was launched with an formidable imaginative and prescient:
Join international crypto capital with companies in underserved markets by unsecured lending.
Backed by main traders together with Andreessen Horowitz (a16z), Goldfinch turned one of the flagship tasks of the primary era of DeFi RWAs.
a16z Invests $25 Million into Goldfinch, a DeFi Lending Protocol, with Africa the Leading Market
In contrast to most DeFi lending platforms that require debtors to submit crypto collateral, Goldfinch financed actual companies utilizing conventional credit score underwriting, authorized agreements, and cash-flow-based lending.
The mannequin attracted vital consideration as a result of it promised to unravel a longstanding drawback in international finance:
The lack of entry to inexpensive capital for companies in rising markets.
However after a number of years of operation, Goldfinch has concluded that the economics of the mannequin had grow to be more and more tough to maintain.
In accordance with the protocol, investor demand has shifted sharply towards lower-risk RWAs akin to tokenized U.S. Treasuries and money-market merchandise. On the similar time, originating, servicing, and monitoring non-public credit score loans remained operationally intensive and pricey.
The protocol’s expertise has uncovered a rising actuality throughout the RWA sector: whereas blockchain could make capital motion extra environment friendly, it doesn’t get rid of the complexities of underwriting, monitoring, and recovering real-world loans.
Goldfinch’s wind-down due to this fact represents greater than the closure of a single challenge. It serves as a check case for whether or not DeFi can sustainably scale unsecured lending in frontier and rising markets.

The Unique Promise
For years, RWAs have been seen as crypto’s bridge to the actual financial system.
The thesis was compelling.
As a substitute of producing yield from leveraged crypto buying and selling, protocols may finance productive companies and permit traders to earn returns derived from precise financial exercise.
Emerging markets turned a pure goal.
Throughout Africa, Southeast Asia, and Latin America, thousands and thousands of companies face financing gaps regardless of rising demand for credit score. DeFi promised to attach these companies immediately with international swimming pools of capital.
Goldfinch turned one of the earliest and most formidable makes an attempt to show the mannequin may work.
MILESTONE: GoldFinch Finance Crosses $100M in Active Uncollateralized DeFi Loans in Africa
The First Main Warning Signal: Tugende
Lengthy earlier than Goldfinch introduced its wind-down, cracks had already begun to emerge.
One of the protocol’s highest-profile debtors was Tugende, an East African asset-financing firm that gives lease-to-own bikes for bike taxi operators.
In 2021, Tugende Kenya secured a $5 million mortgage by Goldfinch. The deal was broadly seen as a showcase for the way DeFi capital may help financial improvement and monetary inclusion in Africa.
The transaction appeared to validate the RWA thesis:
- World traders funding productive companies.
- Actual-world money flows supporting investor returns.
- Lowered dependence on conventional banks.
- Expanded entry to credit score in underserved markets.
[MILESTONE] African SMEs Among Over 1 Million Borrowers Getting DeFi Loans from GoldFinch DeFi Pools
Nonetheless, the fact proved extra difficult when real-world threat entered DeFi.
In 2022, Goldfinch found that roughly $1.9 million from the Kenyan facility had been transferred to Tugende Uganda with out authorization beneath the unique lending settlement.
The switch highlighted an uncomfortable fact for a lot of DeFi traders.
The dangers threatening the mortgage weren’t technical failures, smart-contract exploits, or blockchain vulnerabilities.
They had been conventional credit score dangers.
The borrower confronted operational challenges, financial pressures, and governance points that will have been acquainted to any standard lender.
Among the many challenges had been:
- Inflationary pressures.
- Rising working prices.
- Cross-border enterprise complexities.
- Weakening monetary efficiency.
- Breaches of lending covenants.
None of these dangers had been solved by tokenization.
The Default That Uncovered the Mannequin
By 2023, Tugende had defaulted on the Goldfinch mortgage.
The protocol warned traders that losses may doubtlessly attain the complete worth of the ability, forcing write-downs and decreasing anticipated yields.
For the broader RWA sector, the default turned one of the earliest large-scale reminders that blockchain infrastructure doesn’t get rid of credit score threat.
The know-how efficiently moved capital throughout borders.
It didn’t assure compensation.
This distinction would later grow to be more and more necessary as traders evaluated the long-term viability of non-public credit score RWAs.
DeFi | Tugende Kenya Defaults on $5 Million (~ 4% of TVL) Loan from GoldFinch DeFi Protocol
Why Emerging Markets Grew to become the Final Stress Take a look at
The Tugende case additionally highlighted a structural problem dealing with DeFi lenders working in Africa and different rising economies.
Many debtors function in environments characterised by:
- Foreign money volatility.
- Inflation shocks.
- Restricted credit score histories.
- Weaker authorized enforcement mechanisms.
- Greater restoration prices.
- Better publicity to financial instability.
Conventional monetary establishments spend a long time constructing techniques to handle these dangers.
Many DeFi protocols tried to recreate these capabilities whereas concurrently working throughout a number of jurisdictions and regulatory environments.
As defaults emerged, traders started reassessing whether or not the extra yield justified the extra threat.
Goldfinch finally demonstrated each the potential and limitations of DeFi credit score.
The protocol proved that blockchain networks can effectively mobilize international capital and direct it towards real economic activity.
[MILESTONE] African SMEs Amongst Over 1 Million Debtors Getting #DeFi Loans from GoldFinch DeFi Swimming pools
🇰🇪
🇳🇬
🇬🇭The GoldFinch protocol provides crypto loans with out requiring crypto collateral which distinguishes them and scaling fairly successfulyhttps://t.co/4m29eSMB6e pic.twitter.com/YRljoWHCey
See additionally
— BitKE (@BitcoinKE) July 18, 2022

Nevertheless it additionally revealed that lending stays basically a credit score enterprise slightly than a know-how enterprise.
Success is determined by:
- Underwriting high quality.
- Borrower choice.
- Mortgage servicing.
- Authorized enforcement.
- Restoration processes.
- Threat administration.
The blockchain layer can enhance effectivity.
It can’t change these capabilities.
Goldfinch’s wind-down coincides with a broader transformation throughout the RWA sector.
Investor capital has more and more flowed towards property akin to tokenized U.S. Treasury payments, money-market funds, and short-duration authorities securities.
These property supply decrease operational complexity, clearer regulatory therapy, and considerably decrease default threat.
Because of this, many of the fastest-growing RWA tasks at the moment deal with bringing present monetary devices on-chain slightly than creating new varieties of decentralized non-public credit score.
“Not all the pieces needs to be onchain.” – Hein, @FlowTraders #ParisBlockchainWeek pic.twitter.com/6AVceHQMDh
— BitKE (@BitcoinKE) April 17, 2026
Key Takeaway
Goldfinch could finally be remembered as one of crucial experiments in DeFi’s try to finance the actual financial system.
Its rise demonstrated that blockchain may join international traders with companies in frontier markets.
Its struggles demonstrated that credit score threat, governance failures, and financial shocks stay simply as related on-chain as they’re in conventional finance.
The Tugende default was an early warning.
The protocol’s wind-down often is the ultimate affirmation that scaling unsecured non-public credit score by DeFi is way more durable than tokenizing authorities bonds.
For the following era of RWA tasks, the lesson is more and more clear:
Know-how can transfer capital, however sustainable lending nonetheless is determined by the basics of credit score.
EXPERT OPINION | Tokenization Alone Will Not Fix Illiquid Assets, Say Industry Experts
Keep tuned to BitKE for deeper insights into DeFi developments globally.
Be part of our WhatsApp channel here.
Observe us on X for the most recent posts and updates
Associated