
A UK funding supervisor with over £286 billion ($377B) in property underneath administration is testing a sharper model of fund tokenization with BAGEY: public blockchains are getting used as a part of the document that claims who owns a regulated UK fund.
That lastly strikes the tokenization debate into fund administration relatively than distribution alone. A tokenized fund can nonetheless be a blockchain-shaped declare on a standard product whose decisive ownership document sits elsewhere.
Baillie Gifford is presenting a stronger mannequin, one the place the on-chain document varieties a part of the authorized ownership register itself.
In that model, the token turns into the means by which an investor’s holdings are recorded. The consequence is tangible: if regulated fund ownership can reside natively on public chains, the change is within the fund administration stack, not in crypto market publicity.
Baillie Gifford’s digital property material frames tokenization as an improve to ownership records, settlement, entry, and shopper outcomes. The attraction is that records and processes can move otherwise when ownership is represented on shared rails.
The launch solutions one slim, tokenized-fund query with a certified sure: regulated funds are shifting towards authorized infrastructure on public chains, relatively than blockchain-wrapped variations of current merchandise.
The mannequin nonetheless has to show it will possibly help secondary transfers, around-the-clock settlement, or collateral use exterior a managed primary-market setting.
Native issuance shifts the ownership document by tokenization
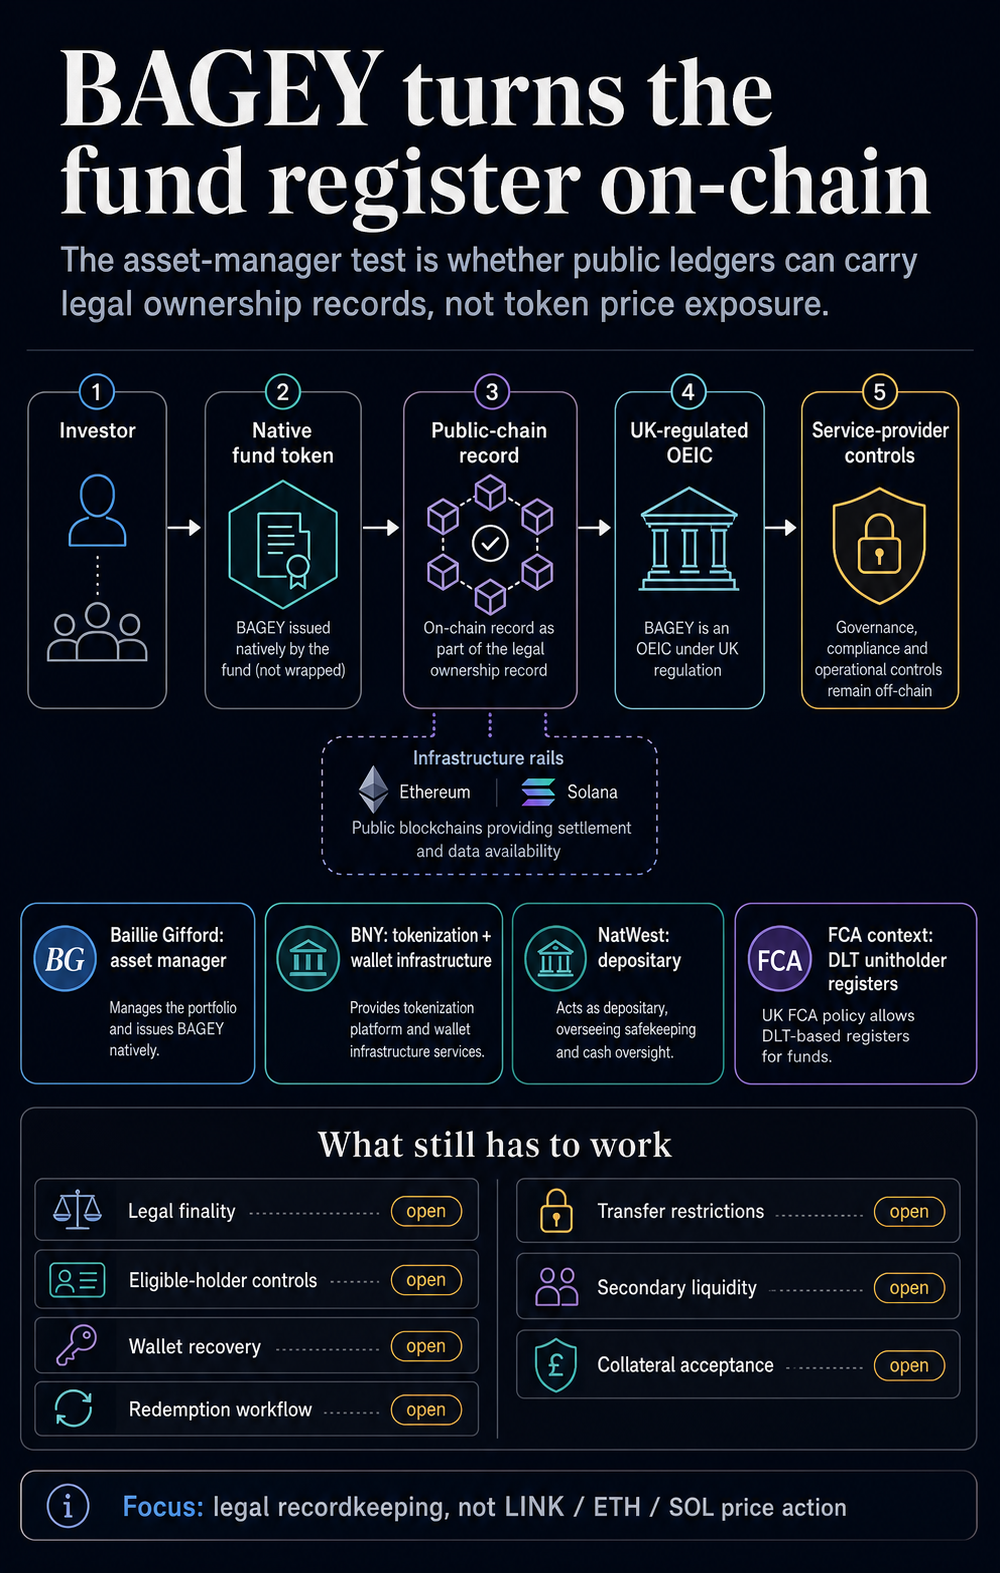
The central declare round BAGEY is native issuance. Baillie Gifford described it as a totally native UK-regulated tokenized fund working by a UK-regulated OEIC construction, with issuance on Ethereum and Solana, BNY offering tokenization and pockets infrastructure, and NatWest Trustee and Depositary Providers performing as depositary.
If the blockchain is the authorized register, then the fund administrator, custodian, switch agent, depositary, and investor are coordinating round greater than a personal database that later reconciles with a token.
The shared ledger turns into a part of the document that claims who owns what.
That’s materially totally different from a tokenized wrapper. A wrapper can provide buyers blockchain-based entry to fund publicity whereas protecting the legally decisive register inside conventional infrastructure.
It might probably nonetheless be helpful, however the operational heart of gravity stays off-chain. BAGEY’s extra necessary declare is that the document layer itself has moved.
| Mannequin | The place ownership lives | What the token does | Essential query |
|---|---|---|---|
| Native tokenized fund | The on-chain document is offered as a part of the fund ownership register | Records the investor’s direct holding within the regulated fund | Can authorized, custody, switch, and restoration controls maintain up in manufacturing? |
| Tokenized wrapper | A separate fund or administrator document stays the decisive supply | Represents entry to an off-chain product | Does the wrapper add actual utility past distribution? |
| Crypto publicity product | Conventional product records stay central | Offers publicity to a token, chain, or associated technique | How does the asset worth carry out? |
That distinction retains LINK, ETH, and SOL worth motion secondary. Chainlink amplified the launch, and Ethereum and Solana present the public-chain infrastructure, however the information facilities on whether or not fund ownership will be recorded natively on shared public ledgers inside a regulated construction.
The UK backdrop turns tokenization into fund plumbing
The UK backdrop is central. The Monetary Conduct Authority printed PS26/7 on fund tokenization on April 30, setting out how licensed fund managers can use distributed ledger expertise inside the current licensed fund framework.
The coverage assertion covers tokenized fund fashions and DLT-based unitholder registers, offering BAGEY with a regulatory framework past an remoted product launch.
CryptoSlate beforehand lined the UK’s move to approve tokenizing FCA-authorized investment funds. That earlier shift issues as a result of BAGEY now backs the coverage route with a selected asset supervisor, fund construction, service-provider stack, and public-chain implementation.
It additionally follows tokenized-fund experiments wherein Chainlink, Swift, UBS, and others examined subscriptions and redemptions, in addition to transfer-agent automation. These pilots demonstrated that conventional fund workflows could possibly be built-in with blockchain techniques.

BAGEY pushes the query additional. The related subject is whether or not the document of regulated fund ownership can reside natively on public-chain infrastructure, relatively than whether or not a single workflow will be automated.
For asset managers, that shifts the burden of proof. A tokenized fund wrapper will be evaluated based mostly on entry, distribution, and investor demand.
A local fund document have to be assessed for authorized finality, operational resilience, controls over eligible holders, failed or mistaken transfers, pockets loss, sanctions screening, redemption timing, and the purpose at which a blockchain entry turns into enforceable towards the fund.
These are sensible back-office particulars. They decide whether or not the token can ever develop into helpful past issuance and redemption.
A fund token that may be trusted because the authorized ownership document might, in principle, move extra simply between authorized holders and settle exterior standard market hours as a result of counterparties can see and depend on the ownership document. If these authorized and operational controls stay restricted, tokenization stays nearer to a managed distribution channel.
The identical warning applies to collateral. Baillie Gifford’s broader tokenization supplies focus on asset mobility and shopper outcomes, however BAGEY’s launch document alone doesn’t set up that the fund token is already accepted as collateral throughout market venues.
That’s the reason the subsequent disclosures matter as a lot because the launch label: they’ll present whether or not the on-chain register adjustments every day fund operations or primarily adjustments how the product is issued.
The following check is operational proof
BAGEY reveals that a big conventional asset supervisor is prepared to place a regulated fund construction on public-chain rails and describes the outcome as native relatively than wrapped. It additionally reveals that main service suppliers will be introduced into that construction.
BNY’s infrastructure position and NatWest’s depositary position matter as a result of regulated funds don’t develop into authorized infrastructure solely by a wise contract. They want oversight, reconciliation, controls, custody procedures, and investor protections that establishments can defend.
The launch stops in need of exhibiting that tokenized fund items will commerce freely across the clock, develop into broadly accepted as collateral, or substitute the remainder of the fund administration stack. These outcomes require proof of precise switch mechanics, secondary liquidity, investor onboarding, redemption efficiency, and authorized therapy underneath stress.
That’s the subsequent check for tokenized funds. The trade already is aware of that monetary merchandise will be represented on blockchains.
The tougher query is whether or not regulated establishments will deal with public-chain records because the place the place authorized ownership is established, up to date, and relied upon by different market contributors.
If the reply turns into sure, tokenization stops being largely a packaging story. It turns into a change to the plumbing behind fund ownership.
Asset managers would then compete not simply on product publicity, however on how briskly, clear, transportable, and operationally dependable their fund records are.
If the reply stays partial, BAGEY should be necessary, however in a extra restricted approach. It might present that native issuance can work inside a managed surroundings whereas leaving essentially the most consequential market capabilities, together with peer-to-peer switch and collateral use, for later.
For now, BAGEY strikes the dialogue ahead with out ending it. It’s a reside check of whether or not public blockchains can carry a regulated ownership document, relatively than proof that they’ve already changed the previous fund administration stack.