
The U.S. and other rich nations must urgently deal with mounting global debt ranges which are weighing most closely on low-income nations and straining the global monetary system, the top of the International Monetary Fund mentioned Wednesday.


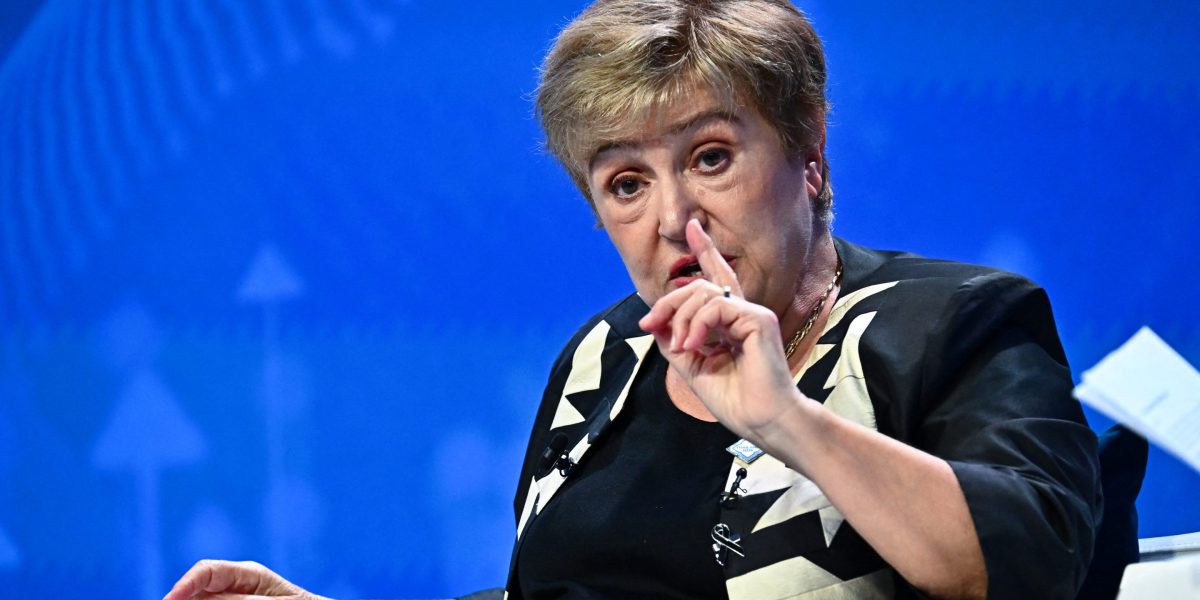
IMF Managing Director Kristalina Georgieva mentioned Treasury Secretary Scott Bessent and other U.S. leaders acknowledge that the federal deficit and nationwide debt are too excessive. However financial progress alone wouldn’t be sufficient to deal with the nation’s greater than $40 trillion in nationwide debt, she mentioned.
In the meantime, rising bond yields, reflecting larger premiums demanded by buyers for taking on higher threat, have been disrupting monetary markets.
“We consider that progress, in fact, helps, however it can not ship quick sufficient the required changes,” Georgieva mentioned on the autumn assembly of the IMF and World Financial institution in Bangkok.
“There is no magic,” she mentioned, including that other measures can be wanted. “It’s important to go in a path of tightening, bringing it down, bringing the deficit down.”
‘Fiscal consolidation’ faces challenges
Rising debt ranges and global inflation, partly ensuing from excessive power prices attributable to the Iran war, have pushed rates of interest to multidecade highs, including to the burdens of the world’s poorest nations.
Efforts to carry debt below management with what Georgieva and other specialists name “fiscal consolidation” have suffered setbacks from heavy spending in the course of the COVID-19 pandemic and since.
“Fiscal dangers are rising, and a correct response is largely absent in lots of nations,” mentioned Rodrigo Valdes, director of the IMF’s Fiscal Affairs Division. “And in main superior economies, the impact of fiscal indiscipline doesn’t cease on the border. It travels to the remainder of the world.”
“Among the many world’s poorest nations, curiosity funds have reached historic highs relative to income, and declining quantities of support are creating gaps that some nations have been unable to finance,” the IMF’s newest Fiscal Monitor mentioned.
That is forcing nations to make onerous selections between supporting their most susceptible individuals and assembly their debt reimbursement obligations.
“The Global South is paying the value for rising rates of interest in wealthier nations,” U.Okay. Overseas Secretary Ed Miliband mentioned at an occasion on the sidelines of the IMF conferences.
“We’d like a brand new deal on debt, a deal that helps nations to repay over longer time horizons and, crucially, refinancing with higher charges to present growing nations valuable fiscal area,” he mentioned.
Nations need assistance with job creation and funding
The median growing nation pays thrice as a lot in curiosity as developed nations, mentioned Alexander De Croo, former Belgian prime minister and administrator of the United Nations Improvement Programme (UNDP).
On common, practically 10% of presidency spending goes towards debt repayments. Excessive gasoline and fertilizer costs, the consequences of the El Niño climate phenomenon and rising borrowing prices have left many low-income nations with little room to recuperate.
“I imply, we don’t see actually a light-weight on the finish of the tunnel,” De Croo advised The Related Press.
Creating jobs is one other high precedence, notably because the rising use of artificial intelligence threatens to make many conventional occupations out of date. Greater than 1.2 billion younger persons are anticipated to enter the global workforce over the following decade or so, whereas forecasts recommend solely 400 million internet new jobs will likely be created.
The UNDP this week introduced its “Jobs for Prosperity” initiative to carry collectively governments, improvement banks — such because the World Financial institution — and non-public companies to encourage funding in sectors akin to tourism, healthcare and meals processing.
The initiative and associated efforts will assist nations appeal to funding by strengthening governance and insurance policies and growing pipelines of “investible initiatives,” De Croo mentioned. “These are issues which are possible. It’s been confirmed that you are able to do it in lots of locations of the world,” he added.
Individually, the IMF, Financial institution of Thailand and World Financial institution Group introduced a “Bangkok Blueprint” on Wednesday to fight cybercrime, monetary fraud and on-line scams.
The announcement got here a day after cyberattacks triggered refrigeration methods to overheat at tons of of shops in France.
___
Related Press journalists Haruka Nuga and Tian Macleod Ji contributed to this report.